


Managing rental income, owner distributions, operating expenses, reserves, and tenant security deposits across multiple properties calls for clear financial organization. As a property manager, you may need property-level records and banking accounts appropriately titled for each applicable legal owner or client-fund arrangement. Maintaining separate bank logins across properties, owners, and entities can spread financial information across multiple workflows. Baselane brings property and entity-level banking into one platform.
Sub-accounts can help organize funds, but their structures differ. Some banking services track clients or beneficiaries within a master escrow account, while others provide checking sub-accounts or virtual accounts associated with a particular business entity. A separate account number does not, by itself, establish separate legal ownership or may not satisfy rules for holding tenant funds. For example, Florida's security deposit statute specifies account location, segregation, and interest requirements for certain residential deposits.
This guide covers seven banking and escrow-management options and the property management workflows each supports.
Own your time,
not just your properties
Make your finances work harder, so you don’t have to.
Key takeaways
- Baselane centralizes property and entity finances: Baselane offers unlimited property-specific checking and savings accounts with no monthly account maintenance fees. Separate accounts can help property managers organize operating funds, owner funds, reserves, and security deposits where permitted across properties and entities.
- Separate account structures support growing portfolios: Baselane allows property managers to organize multiple properties and supported entities under one login, helping reduce account sprawl as owner and unit counts grow.
- Sub-account types serve different purposes: Escrow sub-accounting systems can allocate pooled client funds to individual beneficiaries. Business-checking sub-accounts can divide operating money by property, budget, or expense category. The account's legal owner and permitted uses remain important distinctions.
- Interest and deposit insurance depend on account details: Annual Percentage Yield (APY) expresses annualized interest earnings, including compounding, on eligible balances. Baselane savings accounts offer up to [v="apyvalue"] APY².
- Security deposit handling must follow applicable law: A dedicated sub-account can support deposit tracking, while legal custody depends on state-specific account titling, segregation, institution location, and any interest owed to tenants. For example, Florida Statutes section 83.49 illustrates these distinctions.
Quick overview: bank accounts with sub-accounts for property managers
1) Baselane
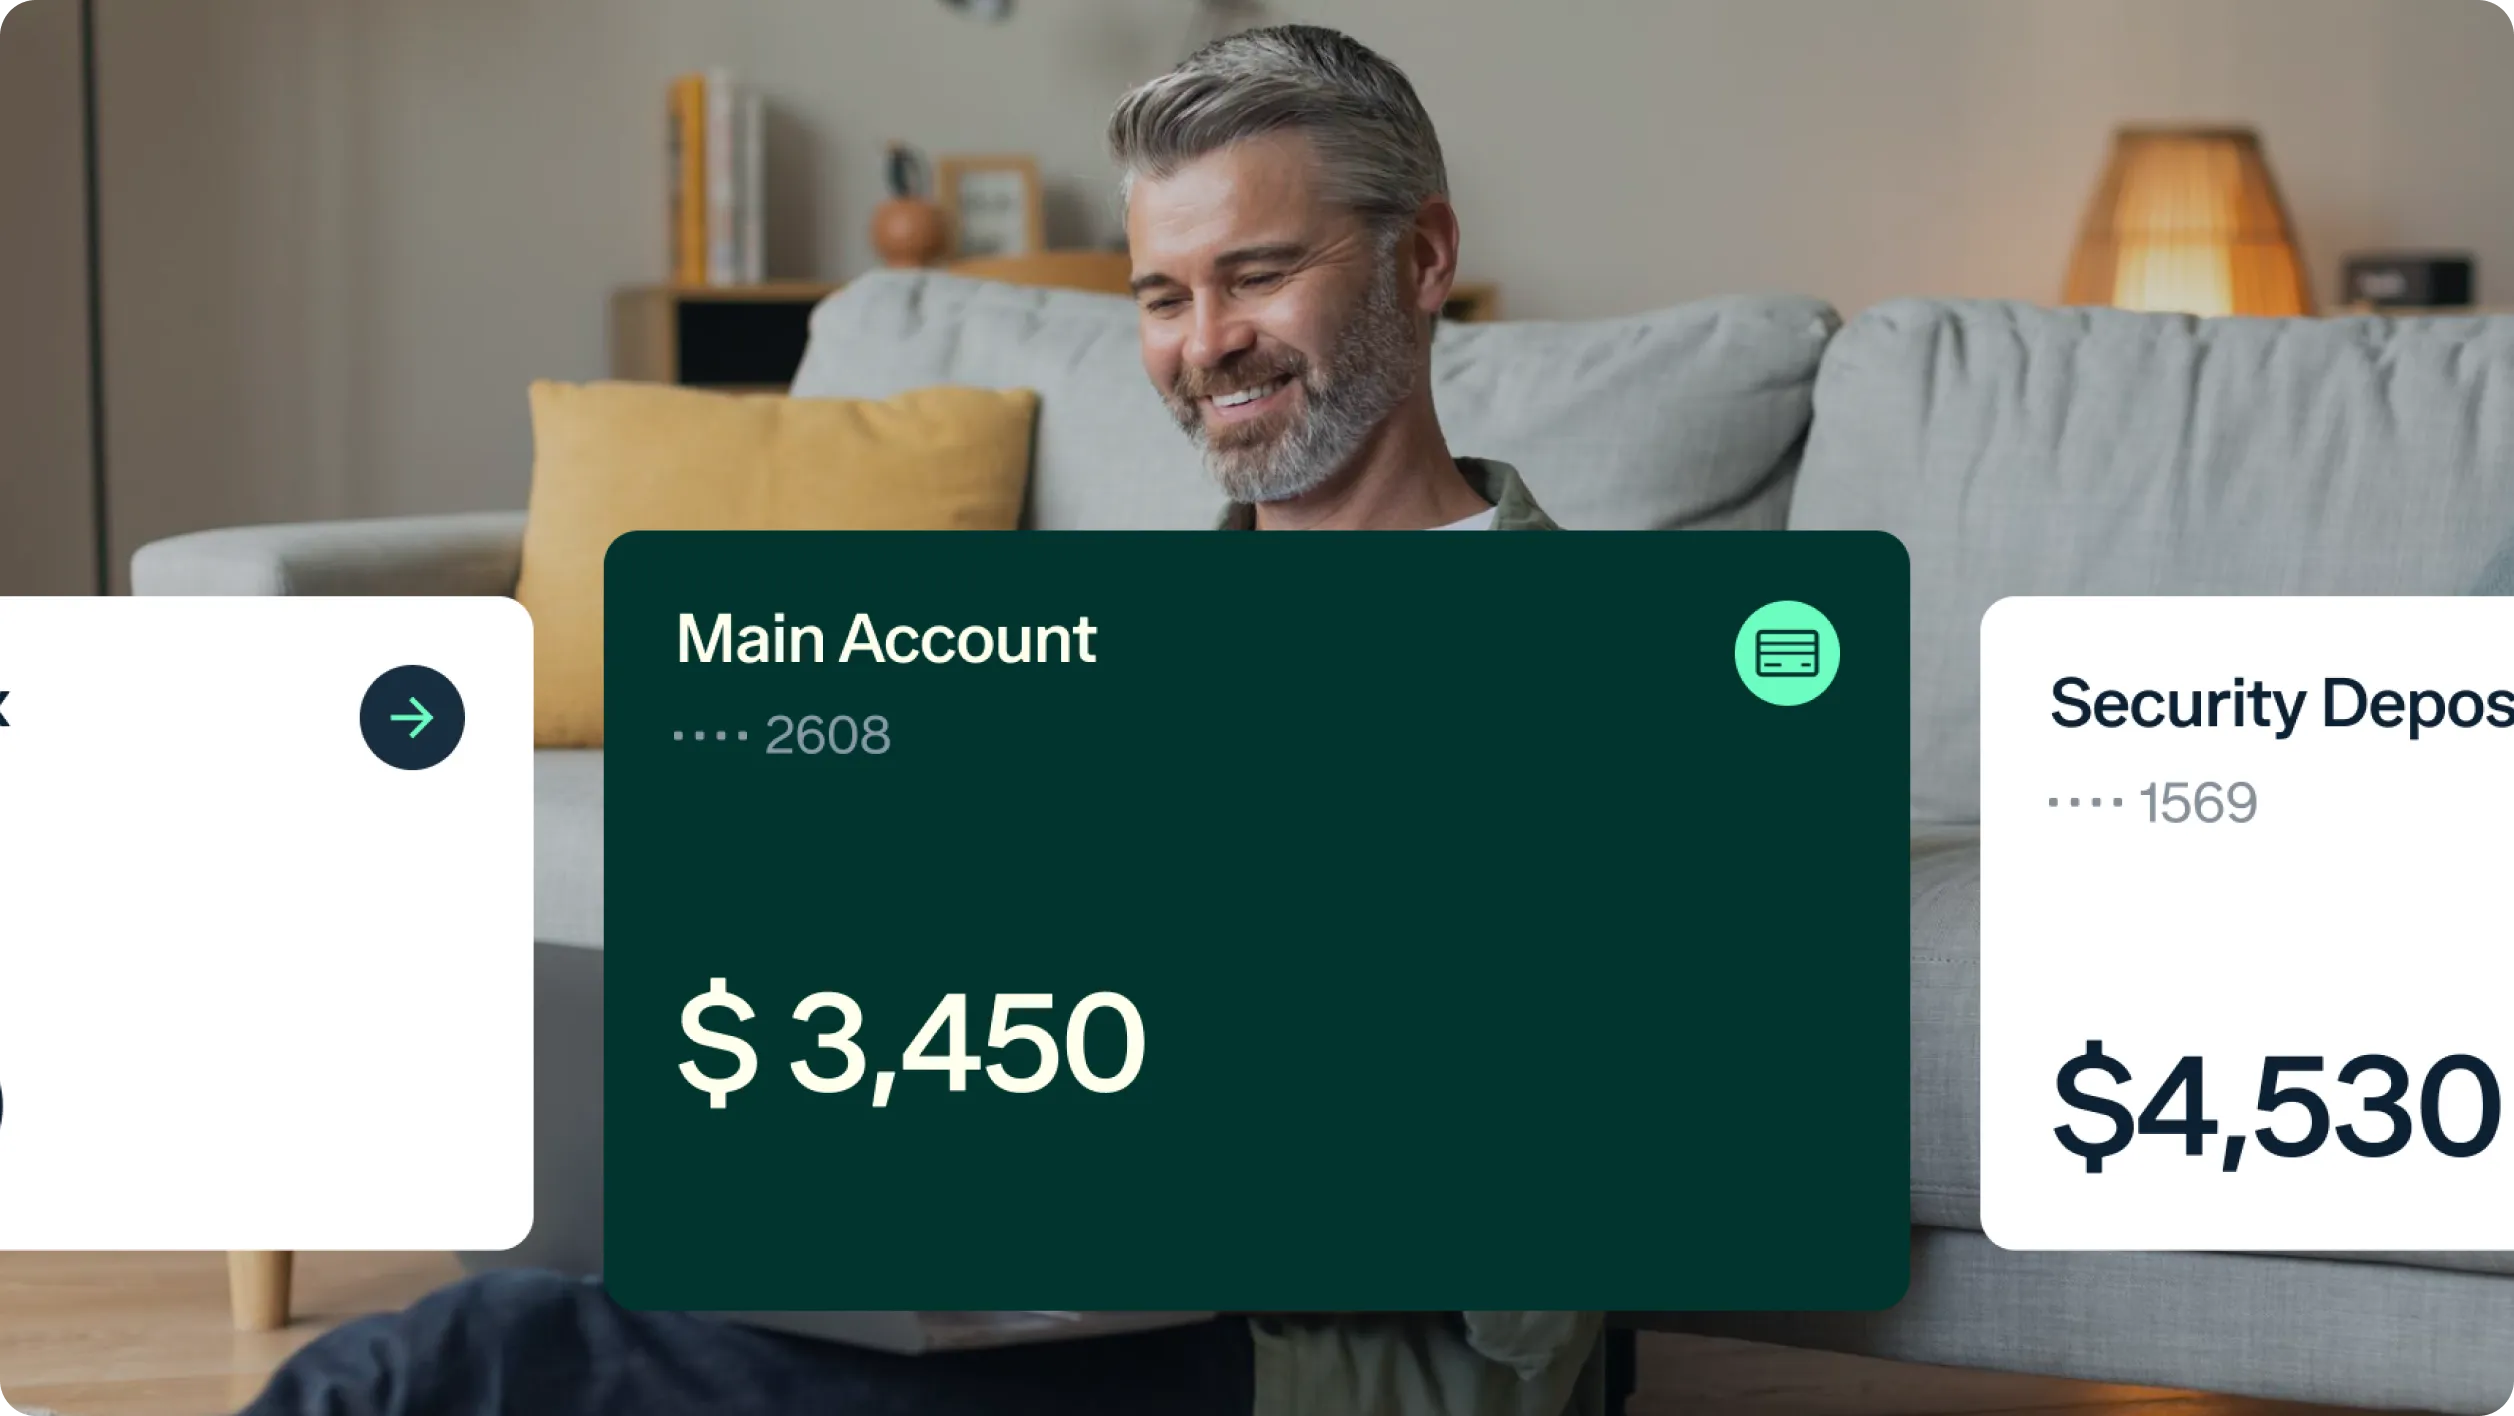
Baselane is a banking platform for property managers and multi-property real estate operators. It brings property- and entity-level banking under one login, helping teams organize accounts across multiple properties and supported entities . Property management operators can create unlimited checking and savings accounts for each property and supported legal entities, then review associated financial activity through one dashboard.
Key capabilities for property managers
- Unlimited property-specific accounts: Baselane allows property managers to create checking and savings accounts for each property, operating funds, maintenance budgets, deposits, and other property-specific purposes, with no monthly account maintenance fees or minimum balance requirements.
- Multi-entity account management: Baselane supports accounts for unlimited entities under one login, helping property managers organize owner funds, operating funds, reserves, and other property-specific balances without juggling separate banking logins. .
- Owner and vendor payments: Same-day ACH can help property managers move funds for owner distributions and vendor payments faster.
- PMS-friendly transaction records: Separate accounts and clear transaction-level banking data can make it easier to match deposits and payments back to the correct property or owner during PMS reconciliation.
- Debit card spending controls: Baselane provides physical and virtual debit cards with spending limits and card controls for property-related expenses. For example, property managers can create virtual cards for maintenance costs.
- High interest earnings: Eligible savings balances earn up to [v="apyvalue"] APY², subject to variable rates and applicable eligibility conditions.
Property management use cases
Baselane allows property managers to organize owner and operating funds, maintenance spending, and reserves under the relevant property and entity. Separate operating accounts can help maintain property-level transaction histories.
For security deposit tracking, you can create dedicated checking or savings accounts to hold tenant security deposits. These accounts keep deposits separate and organized for proper record-keeping. Baselane Banking accounts are provided through Thread Bank in Tennessee. State-specific custody, financial institution location, account titling, segregation, and tenant-interest requirements determine which arrangements can be used for a given deposit. Because state requirements for holding security deposits vary, property managers should confirm their state’s guidelines. A state-by-state guideline can be found here. External security deposit accounts can also be connected in Baselane for additional tracking.
Baselane's integrated workflow
Baselane combines account organization with banking controls and exportable transaction records. It can work alongside property management systems used for operational and trust-accounting workflows, while property and entity-level accounts provide a common view of the associated banking activity.
2) Capital One Escrow Express
Capital One Escrow Express is an escrow sub-accounting service for businesses holding or administering client funds. Its structure uses a master escrow account to hold deposits, with funds allocated to identified client sub-accounts through an online platform.
Key capabilities
- Master escrow structure: Client funds enter a master escrow account held for the benefit of clients and are allocated to sub-accounts associated with the relevant beneficiaries.
- Tenant Security configuration: The service includes Tenant Security, Attorney Trust/IOLTA, and Standard Escrow product configurations, with account-specific terms.
- Online administration: Capital One's online escrow portal supports access to escrow records, sub-account opening and closing, allocations, disbursements, and transaction history.
- User permissions: Administrators can assign access and permission levels for designated users.
- Interest and documentation: Interest calculations, statements, reports, and applicable 1099 handling support beneficiary-level recordkeeping.
Property management use cases
Capital One Escrow Express addresses workflows in which a property management business holds tenant deposits or other funds for identified clients. Its master-account and sub-account design supports allocation of pooled funds and documentation of account activity. Legal responsibilities for custody, permitted transactions, reconciliation, and deposit disbursement remain governed by the escrow agreement and applicable law.
Organizational fit
The service is oriented toward businesses administering client funds through a defined escrow banking relationship rather than simply partitioning ordinary operating budgets. It is relevant to teams managing beneficiary records, interest allocations, and recurring escrow reporting.
3) FNB Escrow Management
FNB Escrow Management, provided by First National Bank, supports escrow sub-account administration through the bank's treasury management services. Its published structure pairs a master escrow holding account with a separate business checking account for deposits and disbursements.
Key capabilities
- Master account administration: The bank's system maintains beneficiary-level escrow records under a master holding account.
- Online sub-account servicing: Authorized users can open, fund, administer, and close escrow sub-accounts through a digital system.
- Consolidated reporting: Monthly electronic summaries and detailed transaction reports support reconciliation of master-account and sub-account activity.
- Interest administration: Interest tracking and disbursement tools help maintain records for the designated beneficiaries.
- Year-end documentation: FNB advertises preparation and mailing of applicable Form 1099 documents to sub-account holders.
Property management use cases
FNB's service is relevant to property managers maintaining identifiable records for multiple escrow beneficiaries. Its reporting and tax-document functions can be used as part of workflows for security deposits and other client funds. The appropriate beneficiary of interest depends on the deposit arrangement and governing law, including state rules that may assign interest to tenants.
Organizational fit
FNB Escrow Management is structured for organizations that use treasury management banking and need consolidated escrow reporting, sub-account servicing, and recurring documentation for account holders.
4) Hanmi Bank Subaccounts
Hanmi Bank offers sub-account administration for real estate, title and escrow, homeowners association, 1031 exchange, and other client-fund workflows. Its platform emphasizes online servicing, document collection, reporting, and interest administration.
Key capabilities
- Online sub-account management: Authorized users can open, fund, manage, or close sub-accounts and access historical account records.
- Document collection: DocuSign-enabled workflows support the collection and storage of W-9 forms and other compliance documents.
- Interest calculations: The service describes customizable interest calculation and splitting functions for designated sub-account arrangements.
- Consolidated reporting: Account statements and reporting tools organize information across multiple funds and clients.
- Industry-specific workflows: The platform is marketed for property management, escrow transactions, 1031 exchanges, and related real estate activities.
Property management use cases
Hanmi Bank Subaccounts supports organizations that maintain separate records for tenant, owner, or client balances within a banking relationship. Digital document collection and beneficiary-level interest tracking can form part of an escrow administration process.
Organizational fit
The offering is oriented toward client-fund administration, particularly for businesses using detailed interest records, electronic documentation, and consolidated reports.
5) Peoples Escrow Manager
Peoples Escrow Manager is an online escrow administration service offered by Peoples Bank. It provides sub-account servicing, document storage, interest calculations, and reporting tools for organizations handling client funds.
Key capabilities
- Online escrow servicing: Designated users can open, fund, administer, and close eligible escrow sub-accounts through the platform.
- Beneficiary records: Digital account numbering and fund-tracking tools help organize balances associated with individual sub-accounts.
- W-9 and document handling: DocuSign integration supports digital collection and storage of tax and account documents.
- Interest administration and reporting: Customizable interest calculations, account statements, and historical reporting support escrow recordkeeping.
- Software connectivity: Peoples describes an API-first capability for connecting escrow workflows with in-house systems. Implementation depends on the supported technical configuration.
Property management use cases
Peoples Escrow Manager can support property management companies that maintain client-fund records, interest allocations, and digital documentation. Its online administration features are relevant where sub-account transactions and reporting are part of a recurring operational process.
Organizational fit
The service is structured for organizations using online escrow administration with document workflows and potential connectivity to internal systems. Its emphasis is on escrow records and servicing rather than general-purpose property budgeting.
6) C&N Bank Property Managers Package
C&N Bank's Property Managers Package brings together ZEscrow, treasury management, and fraud-prevention services. The package is designed around escrow-related banking and cash management through a regional bank relationship.
Key capabilities
- ZEscrow sub-account administration: The escrow platform supports online account management, sub-account records, reporting, configurable interest handling, and DocuSign-enabled document collection.
- Deposit management: C&N offers mobile and remote deposit capture for eligible business banking relationships.
- Business bill pay: Property managers can manage recurring bills and vendor payments through C&N's business banking tools.
- Treasury management: The package includes business banking services such as bill pay and deposit management.
- Fraud-prevention tools: The package lists Payee Positive Pay and ACH Debit Block among its banking controls for eligible business checking arrangements.
Property management use cases
C&N's package supports escrow administration and day-to-day treasury workflows. ZEscrow organizes escrow sub-accounts and associated records, while its banking tools support deposit management, bill pay, and fraud controls.
Organizational fit
The package is aimed at property management businesses that use regional banking services for escrow workflows, treasury functions, deposit management, and transaction controls.
7) Bluevine
Bluevine offers business checking with sub-accounts that have dedicated account numbers. Its account tools include transfers, debit cards, spending controls, and sub-accounts with dedicated account numbers, with capacity dependent on the business checking plan.
Key capabilities
- Dedicated sub-account numbers: Business checking sub-accounts have individual account numbers and can be used to organize operating budgets, taxes, reserves, and vendor payments.
- Sub-account capacity: Bluevine supports up to five, 10, or 50 sub-accounts, depending on the selected business checking plan.
- Debit cards and permissions: Physical and virtual debit cards can be associated with sub-accounts and configured with spending limits and user permissions.
- Automated transfers: Account holders can define transfers between accounts using rules and scheduled execution.
- Interest and payments: Eligible checking balances may earn interest. The platform also supports business invoicing and payment links.
- Multi-business account access: Bluevine supports management of separate business checking accounts through one login, while sub-accounts organize funds belonging to their associated legal entity.
Property management use cases
Bluevine's sub-accounts can separate ordinary business operating funds by property, expense type, or reserve purpose. Dedicated account numbers, transfers, and spending limits support budgets and outgoing payments under a business's banking relationship.
Organizational fit
Bluevine is oriented toward businesses using digital checking, budget segmentation, account permissions, and online payment tools. Its sub-account model and formal client-fund escrow arrangements are different banking structures, particularly when tenant or owner money is held for another party.
Why Baselane stands out for property managers
Baselane brings property-specific banking and multi-entity account management into a single platform. Its account structure is designed around how property management companies separate operating funds, owner funds, reserves, and security deposits across properties and entities.
Unlimited accounts by property and entity
Baselane provides unlimited checking and savings accounts with individual account numbers and no monthly account maintenance fees. Property managers can designate accounts for operating income, maintenance, reserves, and other purposes while organizing accounts by property and legal entity. This creates a direct connection between bank activity and the associated rental records.
Faster owner and vendor payments
Baselane supports next-day OTA and PMS payouts and same-day ACH for faster owner distributions and vendor payments. Property managers can also save vendor and contractor payment details for recurring operating expenses.
Baselane's Core features provide property and entity-level transaction tracking and tax reporting, with subscription details describing advanced feature eligibility.
Cleaner PMS reconciliation
Separate accounts and transaction-level banking data make it easier to trace activity back to the correct property, owner, or entity and match banking activity with the property management system your team already uses.
High interest earnings
Baselane savings accounts offer up to [v="apyvalue"] APY² on eligible balances, with variable rates and applicable account conditions.
Baselane serves as a banking layer that can work alongside property management tools your team already uses, supporting a connected view of accounts across properties and entities.
FAQs
What is a sub-account and why do property managers need one?
A sub-account is a way to identify and administer funds separately within a wider banking arrangement. An escrow service may allocate amounts held in a master account to individual clients or beneficiaries, while a checking platform may provide separate account numbers for operating budgets. Property managers use these structures to organize rental funds, reserves, and client balances. The legal owner of the funds, account titling, and applicable custody rules determine how those accounts can be used. Creating a sub-account for one LLC does not automatically establish a bank account legally owned by another LLC.
How do sub-accounts affect fund ownership and deposit protection?
A sub-account's label or separate account number does not, by itself, establish a new legal depositor. With Baselane, FDIC insurance is available for funds deposited via Thread Bank, Member FDIC. Pass-through insurance coverage is subject to conditions.¹
Can these accounts be opened online without visiting a branch?
Baselane offers digital applications for checking and savings accounts and online creation of additional property-specific accounts after account approval. Bluevine also offers digital business checking and online sub-account setup. Capital One Escrow Express, FNB Escrow Management, Hanmi Bank Subaccounts, Peoples Escrow Manager, and C&N's ZEscrow offer online escrow or sub-account administration within their respective banking arrangements.
How do sub-accounts help with tax preparation for rental properties?
Sub-accounts can organize banking activity by property or entity, making transaction records easier to review and export for tax preparation. Property managers should still rely on their PMS, accounting system, and tax professional for the complete financial records needed for filing.
Which bank account is best for managing security deposits across multiple properties?
The best bank account for managing security deposits fits your organizational and compliance requirements. Baselane provides unlimited dedicated checking and savings accounts for organizing security deposit records by property, with no monthly account maintenance fees. These accounts are provided through Thread Bank in Tennessee. State law determines which deposit-holding arrangements are required, which can include an in-state financial institution, a specific legal account title, separation from operating funds, or interest owed to tenants. Capital One Escrow Express, FNB Escrow Management, Hanmi Bank Subaccounts, Peoples Escrow Manager, and C&N's ZEscrow offer escrow sub-account administration for applicable client-fund arrangements. Neither the number of sub-accounts nor property-level tracking establishes statutory compliance on its own.
What features matter when choosing bank accounts for property management?
Relevant considerations include entity separation, security deposit requirements,, the number and type of sub-accounts,, interest treatment, FDIC coverage, transfer limits, team access, and how cleanly bank data can be reconciled with the PMS. Account features should match the funds being managed, whether rental operating income, property reserves, owner balances, or tenant deposits. Baselane connects property and entity-level checking and savings under one login, helping property managers organize banking activity across properties and supported entities.